Table of Contents
ToggleQuestions to Ask Before Requesting a Property Valuation is the core concern for anyone who needs an accurate market estimate. A precise valuation saves time, avoids costly negotiation mistakes, and directs decisions about selling, buying, refinancing, or appealing taxes. This guide gives ten essential questions to ask before requesting a property valuation, so they can move forward confidently in 2026.
Key Takeaways
- Before requesting a property valuation, confirm the valuer’s credentials, local experience, and independence to ensure a credible and unbiased report.
- Ask which valuation methods will be used and request a sample report that includes clear descriptions, photos, comparable sales, and repair cost estimates.
- Understand the valuation costs, expected delivery time, and how fees compare to regional industry standards to balance price, speed, and quality.
- Use the property valuation to set realistic prices, negotiate repairs, or adjust investment strategies based on accurate market evidence.
- Always verify the recency and relevance of comparable sales data used in the valuation to avoid mispricing in volatile markets.
- Request raw comparable data and clarify assumptions in writing to support negotiation, financing, or tax appeal decisions.
Why A Property Valuation Matters And When To Get One
A clear answer: a property valuation provides an evidence-based market value that supports pricing, lending, and tax decisions. Valuations matter because they convert emotion into numbers, they show whether a listing price is realistic, whether an offer overpays, or whether a refinance will improve loan terms.
When to get one: before listing a property (to set price), before making an offer (to avoid overpaying), during refinancing (to confirm equity), when settling an estate, if disputing property taxes, or when reviewing portfolio performance. For example, a seller who ordered a valuation two weeks before listing discovered $18,500 in overlooked deferred maintenance that reduced the asking price and prevented a later price drop after three weeks of offers.
Practical warning: a valuation is a snapshot, not a guarantee. Markets shift: comparable sales from 90 days ago may lose relevance in a rising market. So ask the valuer how recent their comps are and whether they adjusted for recent neighborhood trends.
Why this matters now: in 2026 some markets remain volatile, and lenders are stricter about loan-to-value ratios. An accurate valuation reduces the risk of a failed sale or a loan denial.
Who Will Carry Out The Valuation — Credentials, Experience, And Independence
Direct fact: the valuer must be licensed, experienced in the local market, and independent from the transaction to be credible. Confirm registration or licensing with the regional regulator and ask for the valuer’s designation (for example, Royal Institution of Chartered Surveyors, or equivalent local bodies).
Ask for proof of: professional registration number, years of local experience, sample reports from similar properties, and professional liability insurance limits. A valuer with ten years’ experience in a suburb will usually spot micro-market shifts that a national appraiser misses.
Independence matters: if the valuer has any financial tie to the buyer, seller, or broker, the result can be biased. Ask, plainly: “Do you have any financial interest in this transaction?” and request a written conflict-of-interest statement.
Vulnerable moment: one owner once accepted a discounted appraisal from a broker-recommended valuer and later learned the report excluded interior photos. That error cost them three negotiation points. Lesson learned: insist on full documentation and verify the valuer’s independence in writing.
Link: to understand site services that support valuation users, review the site overview.
Methodology, Scope, And What The Report Will Include
Key point: ask which valuation methods will be used and what the final report will include. Typical approaches are the sales comparison approach, income approach, and cost approach, valuers often use a combination depending on property type.
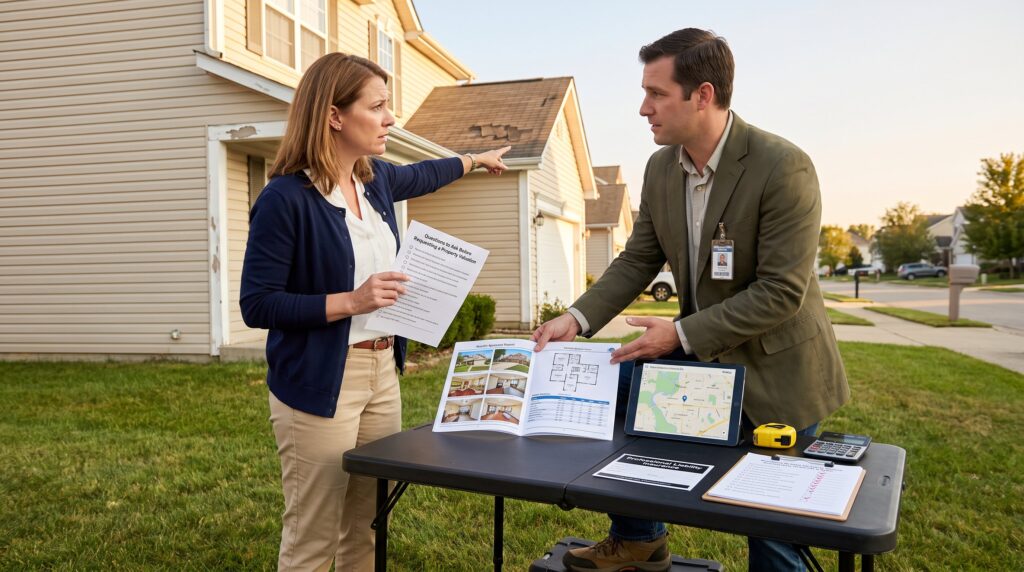
Ask: which approach applies to this property and why: whether the inspection is interior and exterior, desktop-only, drive-by, or full site inspection: and which comparables will be used. Request a sample report to check clarity and depth.
Report contents to expect: a clear property description, condition notes, interior and exterior photos, floor plans or measurements if available, comparable sales or rental evidence, adjustments and calculations, valuation method, assumptions and limitations, and the final value estimate. If the property generates income, the report should show cap rate calculations, gross rent multipliers, and projected yields.
Concrete detail: insist on dates for comparable sales, a comp sold 120 days ago requires stronger adjustment than one sold 20 days ago. Also ask whether the valuer will include recent repair costs as line items: one investor saved $6,300 in negotiation leverage by showing a valuer’s documented repair estimate.
Practical question to ask the valuer: “Will you provide the raw comparable data with sale dates and addresses?” That data helps buyers and lenders verify the result.
Costs, Timing, And How The Valuation Affects Your Options
Immediate answer: valuation fees vary with property complexity, location, urgency, and report depth: turnaround time ranges from same day to several weeks. Typical residential appraisals often cost between a few hundred to over a thousand dollars depending on region and detail.
Ask specifically: what is the fee, what is included, are there extra charges for rush delivery or detailed market commentary, and what is the expected delivery date? Also ask whether the valuer offers a limited desktop valuation at lower cost and what trade-offs apply.
Evidence and numbers: regional averages matter. National resources report typical home appraisal costs and factors that affect pricing: ask the valuer to justify their fee relative to those industry norms. For typical homeowner appraisal ranges, see the breakdown of appraisal costs that explains common price drivers.
How valuation results change options: a higher-than-expected valuation lets a seller price confidently or supports stronger refinance terms. A lower-than-expected valuation can force a price reduction, pause a mortgage, or trigger renegotiation. For investors, valuation affects acquisition strategies, projected yield, and financing capacity, a 2% valuation variance on a $450,000 purchase changes loan eligibility by thousands.
Practical warning: paying for the cheapest appraisal can cost more later if the report lacks defensible comparables. Balance price, speed, and report quality when choosing a valuer.
How To Use The Valuation: Next Steps For Sellers, Buyers, And Investors
Straight answer: use the valuation to set price, inform offers, negotiate repairs, or adjust investment models. Each role applies the report differently.
Sellers: start with the valuer’s recommended asking range. Use the condition notes to prioritize two or three repairs that will most improve value. For example, fixing a leaking roof that the valuer flagged avoided a $12,000 buyer concession in one sale. Share the valuation with listing agents to support the asking price in marketing materials.
Buyers: compare the valuer’s estimate to the asking price and structure offers accordingly. If the appraisal is lower than the seller’s price, buyers can request seller concessions, ask for price reduction, or attach an appraisal contingency. Practically, buyers should request the raw comparables to check the valuer’s adjustments and avoid overpaying.
Investors: plug the valuation into yield and cap rate models. Use the report to vet financing, lenders often require an appraisal that aligns within a narrow band of the purchase price. If the valuation reveals lower-than-expected rental income, reassess acquisition price or plan for value-add improvements. A realistic example: an investor adjusted a projected 7% cap rate to 5.5% after the valuation showed higher maintenance costs.
Next steps checklist: 1) confirm the valuer’s assumptions in writing: 2) use the report to prioritize repairs or listing presentation: 3) present the valuation to lenders or tax authorities with highlighted comps: 4) if the report is unfavorable, consider a second opinion or negotiate contingencies.
Related resources: readers can explore how the site explains broader real estate services in a short primer on how to explore services. Additional seller-focused materials are available in the seller resources section to help carry out valuation recommendations.